Maryam Nawaz Loan Scheme 2026: Asaan Karobar Finance Scheme & Card Apply Online
Starting or growing a small business in Pakistan usually means facing one big wall: banks asking for collateral you don’t have, or interest rates that eat up your profits before you even start. The Maryam Nawaz Loan Scheme, officially known as the CM Punjab Asaan Karobar Finance Scheme and Asaan Karobar Card, was launched to remove exactly that barrier. Chief Minister Punjab Maryam Nawaz Sharif officially inaugurated both schemes to give small business owners and entrepreneurs access to interest-free financing, without the usual red tape. This guide walks you through how the scheme works, who qualifies, and exactly how to apply. 8171 Ehsaas Program
What Is the Maryam Nawaz Loan Scheme?
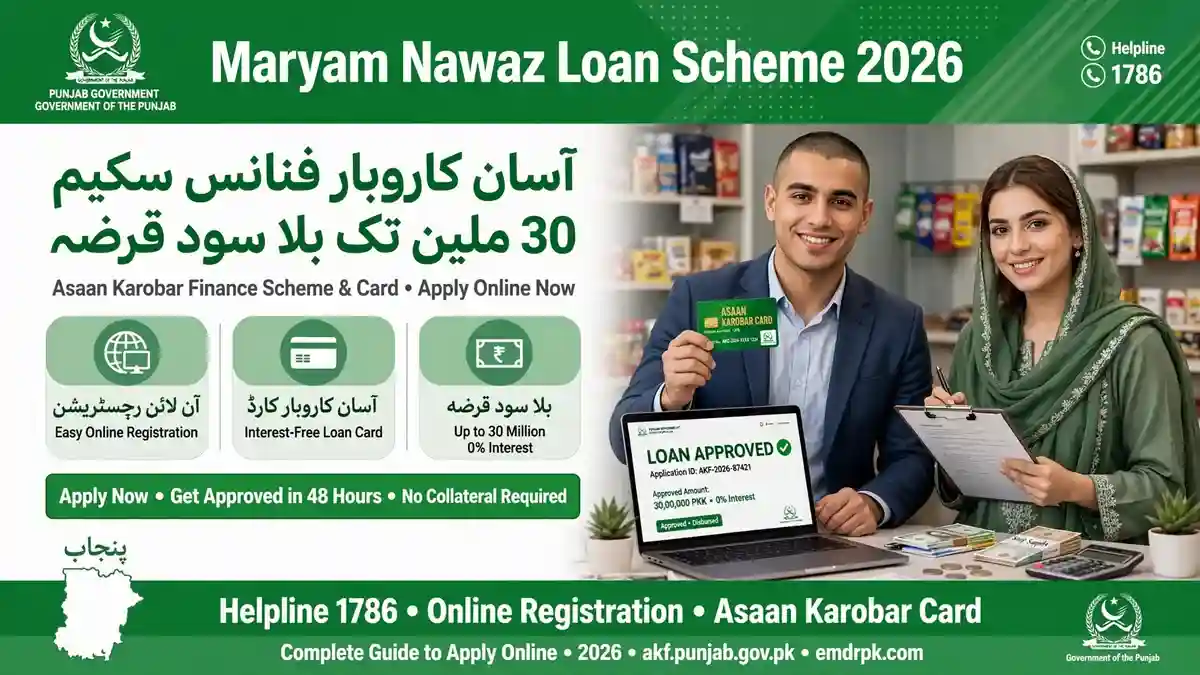
The Maryam Nawaz Loan Scheme is made up of two connected programs run by the Punjab government: the Asaan Karobar Finance Scheme and the Asaan Karobar Card. Both are designed to give Punjab residents interest-free or low-markup access to business capital, with repayments made through easy monthly installments instead of lump-sum repayment. The scheme is a Punjab government initiative run in partnership with the Bank of Punjab and the Punjab Small Industries Corporation (PSIC), and it’s meant to support both people starting a new business and those looking to expand an existing one. Maryam Nawaz Loan Scheme 2026
Asaan Karobar Card vs. Asaan Karobar Finance: What’s the Difference?
These are two separate products under the same umbrella, and knowing which one fits your situation matters: Ehsaas Rashan Program 2026
- Asaan Karobar Card: A digital SME credit card offering interest-free financing of up to roughly Rs. 1 million (with the official announcement citing loans of Rs. 5 lac to Rs. 10 lac through the card). Funds are released in stages and can only be used for business purposes through POS systems or a linked app.
- Asaan Karobar Finance Scheme: A larger financing option, with reported limits ranging from around Rs. 1 million up to Rs. 30 million, split into tiers. Tier 1 financing needs no collateral, just a personal guarantee, while Tier 2 requires security such as property documents.
If you run a small shop or service business and need working capital, the Card is usually the simpler route. If you’re planning a bigger expansion, the Finance Scheme’s higher tiers are built for that.
Eligibility Criteria for the Maryam Nawaz Loan Scheme
While exact figures can shift slightly between guide sources, the eligibility criteria consistently include:
- You must be a resident of Punjab with a valid CNIC.
- Your business must be located in Punjab.
- Age typically falls between 21 and 57 years, though some notices list 25–55, so always confirm on the portal.
- You must be an active FBR tax filer with a valid NTN. Non-filers are generally not eligible.
- A clean credit history, with no loan defaults or overdue payments.
- For new businesses, a simple, workable business plan is required.
- Proof of business premises, whether owned or rented.
Documents You’ll Need
Before applying, gather these: your original CNIC (not expired — you can check this at nadra.gov.pk), your NTN registration, proof of business ownership or rental agreement, bank account details, and a business plan if you’re a new applicant. Having these ready in digital form speeds up the process significantly. CM Punjab Complaint Cell Online,
How to Apply for the Maryam Nawaz Loan Scheme Online
The entire process is digital, with no agents or recommendations needed. Here’s how it works:
- Choose your product — decide whether you’re applying for the Asaan Karobar Card or the Asaan Karobar Finance Scheme.
- Visit the correct official portal. For the Finance Scheme, go to akf.punjab.gov.pk. For the Card, go to akc.punjab.gov.pk.
- Register using your CNIC and a mobile number registered in your own name.
- Fill in your personal and business details carefully, including your NTN and business address.
- Upload your documents, including your business plan if required.
- Submit your application for verification.
- Wait for review. Applications go through credit assessment and eligibility checks, and for larger Finance Scheme tiers, shortlisted applicants may face an interview or a business site visit.
Fees and Repayment Terms
Some fees are commonly reported for the 2026 cycle, though you should confirm exact current figures on the official portal before applying: an application fee of around Rs. 500 for the Card, and higher processing fees for Finance Scheme tiers. For the Card specifically, reported terms include a 3-year duration, a 3-month grace period, and repayment over 33 monthly installments afterward, with 0% markup for the borrower.
This is not a grant — it’s a loan that must be repaid, just without the burden of interest. Treat it with the same seriousness as any bank financing.
Getting Help: The Official Helpline
If you’re unsure about any step, Punjab has activated a dedicated helpline, 1786, specifically for assistance with both the Asaan Karobar Finance Scheme and the Asaan Karobar Card. This is useful if your online application gets stuck or you need clarification on eligibility before applying.
How to Avoid Fake Asaan Karobar Websites
Because this scheme has generated a lot of public interest, several unofficial sites use the same name to attract traffic, and some even appear to have been compromised with unrelated spam content. Protect yourself with these rules:
- Only use akf.punjab.gov.pk or akc.punjab.gov.pk For — no other domain is official.
- Applying is free; never pay anyone claiming to speed up approval. Maryam Nawaz Loan Scheme
- Never share your CNIC, OTP, or NADRA details with anyone outside the official portal.
Final Thoughts
The Maryam Nawaz Loan Scheme gives small business owners in Punjab a genuine, interest-free path to funding that was previously hard to access without collateral or connections. Whether you choose the Asaan Karobar Card for smaller working capital needs or the Asaan Karobar Finance Scheme for larger expansion, the process is fully online and free to apply for. Gather your documents, confirm the latest terms on the official portal, and apply directly — never through a third-party site asking for payment.